Carbon reduction has moved from a corporate sustainability initiative to a strategic business priority for the chemical sector. Companies now face increasing pressure from regulators, investors, customers and supply chain partners to demonstrate measurable progress toward emissions targets.
The chemical industry remains one of the world's most energy-intensive manufacturing sectors. As a result, achieving net-zero ambitions requires action across multiple fronts simultaneously. No single technology can deliver the necessary reductions.
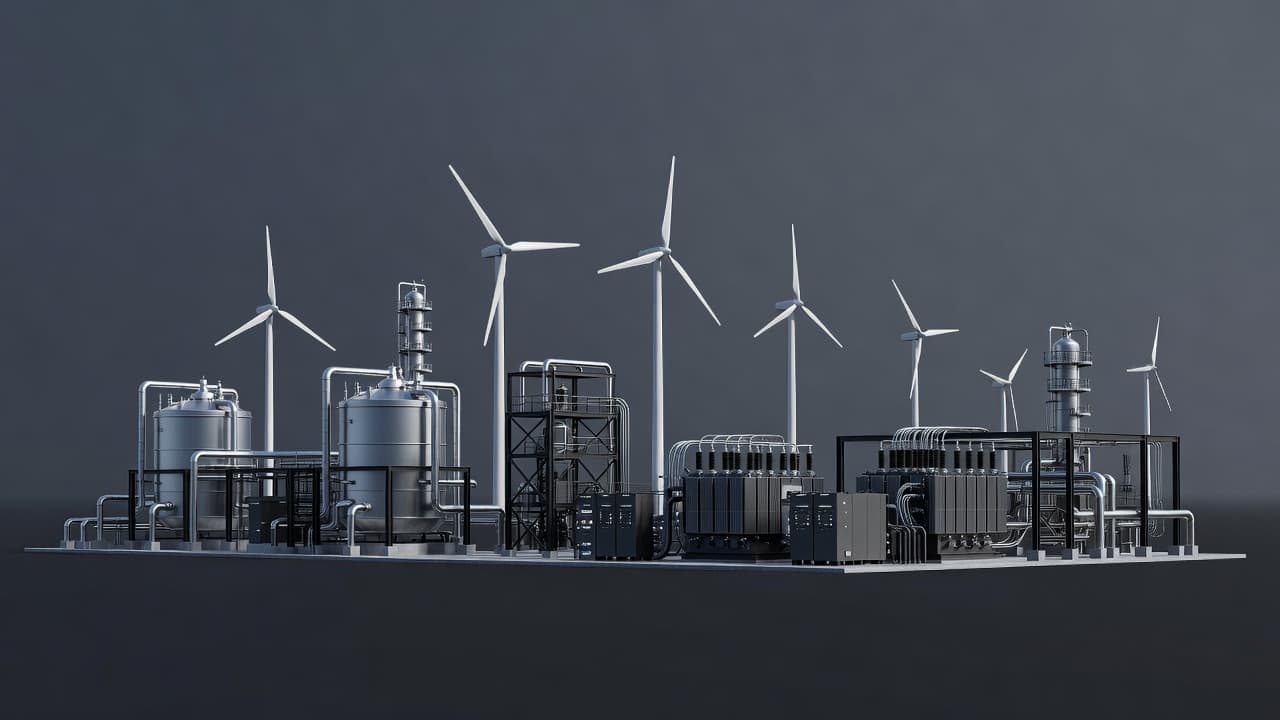
Leading producers are combining energy efficiency improvements, alternative feedstocks, carbon capture systems and supplier engagement programs to reshape the industry's emissions profile through 2035 and beyond.
Why chemical companies face growing decarbonization pressure
Chemical manufacturing sits at the intersection of industrial production and global sustainability goals. Many core products rely on energy-intensive processes that generate significant direct and indirect emissions.
Several forces are accelerating carbon reduction efforts:
Expanding climate disclosure requirements across global markets.
Customer expectations increasingly favor suppliers with lower embedded emissions.
Carbon border mechanisms are influencing international trade competitiveness.
Financial institutions are integrating climate performance into investment decisions.
Major industry participants have already established long-term commitments.
Companies such as BASF, Dow, Covestro and INEOS have announced net-zero ambitions targeting 2040 to 2050, supported by interim 2030 reduction objectives.
These commitments signal that decarbonization has become a core element of long-term business strategy.
Energy efficiency remains the fastest carbon reduction lever
Energy efficiency continues to offer one of the most cost-effective pathways for immediate emissions reductions.
Chemical plants consume substantial quantities of heat, steam and electricity. Improving how these resources are generated and utilized can significantly reduce carbon intensity.
Common efficiency initiatives include:
Process heat integration to recover and reuse waste heat throughout facilities.
Upgrading equipment such as compressors, pumps and motors to higher efficiency standards.
Advanced process control systems that optimize energy consumption in real time.
Steam system modernization to minimize losses and improve performance.
Electrification also plays an increasingly important role.
Replacing fossil fuel-based steam generation with electrically powered alternatives enables companies to leverage lower-carbon electricity sources as grid mixes evolve.
For many producers, energy efficiency provides attractive economics because operational savings can partially offset investment requirements.
Feedstock switching is reshaping chemical production pathways
Traditional chemical production often depends on natural gas and other fossil-derived feedstocks. Feedstock switching offers an opportunity to address emissions embedded within manufacturing processes.
Two important examples include ammonia and methanol production.
Conventional synthesis routes rely heavily on fossil resources. Emerging approaches utilize green hydrogen generated through renewable-powered electrolysis.
Potential advantages include:
Reduced direct emissions from production processes.
Alignment with customer demand for lower-carbon products.
Greater compatibility with future carbon pricing frameworks.
Challenges remain, particularly around renewable electricity availability and production costs.
However, declining renewable energy costs continue to improve the long-term outlook for green feedstock adoption.

Chemical recycling supports circular feedstock strategies
Chemical recycling is emerging as an important component of chemical industry decarbonization.
Unlike mechanical recycling, chemical recycling technologies break down waste materials into feedstocks that can re-enter production systems.
Pyrolysis represents one of the most prominent approaches.
The process converts plastic waste into pyrolysis oil, which can partially replace virgin fossil feedstocks within steam crackers.
Benefits include:
Diversion of difficult-to-recycle materials from disposal pathways.
Reduced dependence on newly extracted fossil resources.
Support for circular economy objectives.
Several producers continue investing in commercial-scale recycling infrastructure as part of broader sustainability strategies.
While challenges related to scale and economics remain, chemical recycling offers a pathway toward lower-carbon material flows.
Carbon capture projects gaining momentum across the sector
Carbon capture and storage has become an increasingly important tool for managing residual emissions.
Certain chemical processes generate emissions that remain difficult to eliminate through efficiency improvements alone.
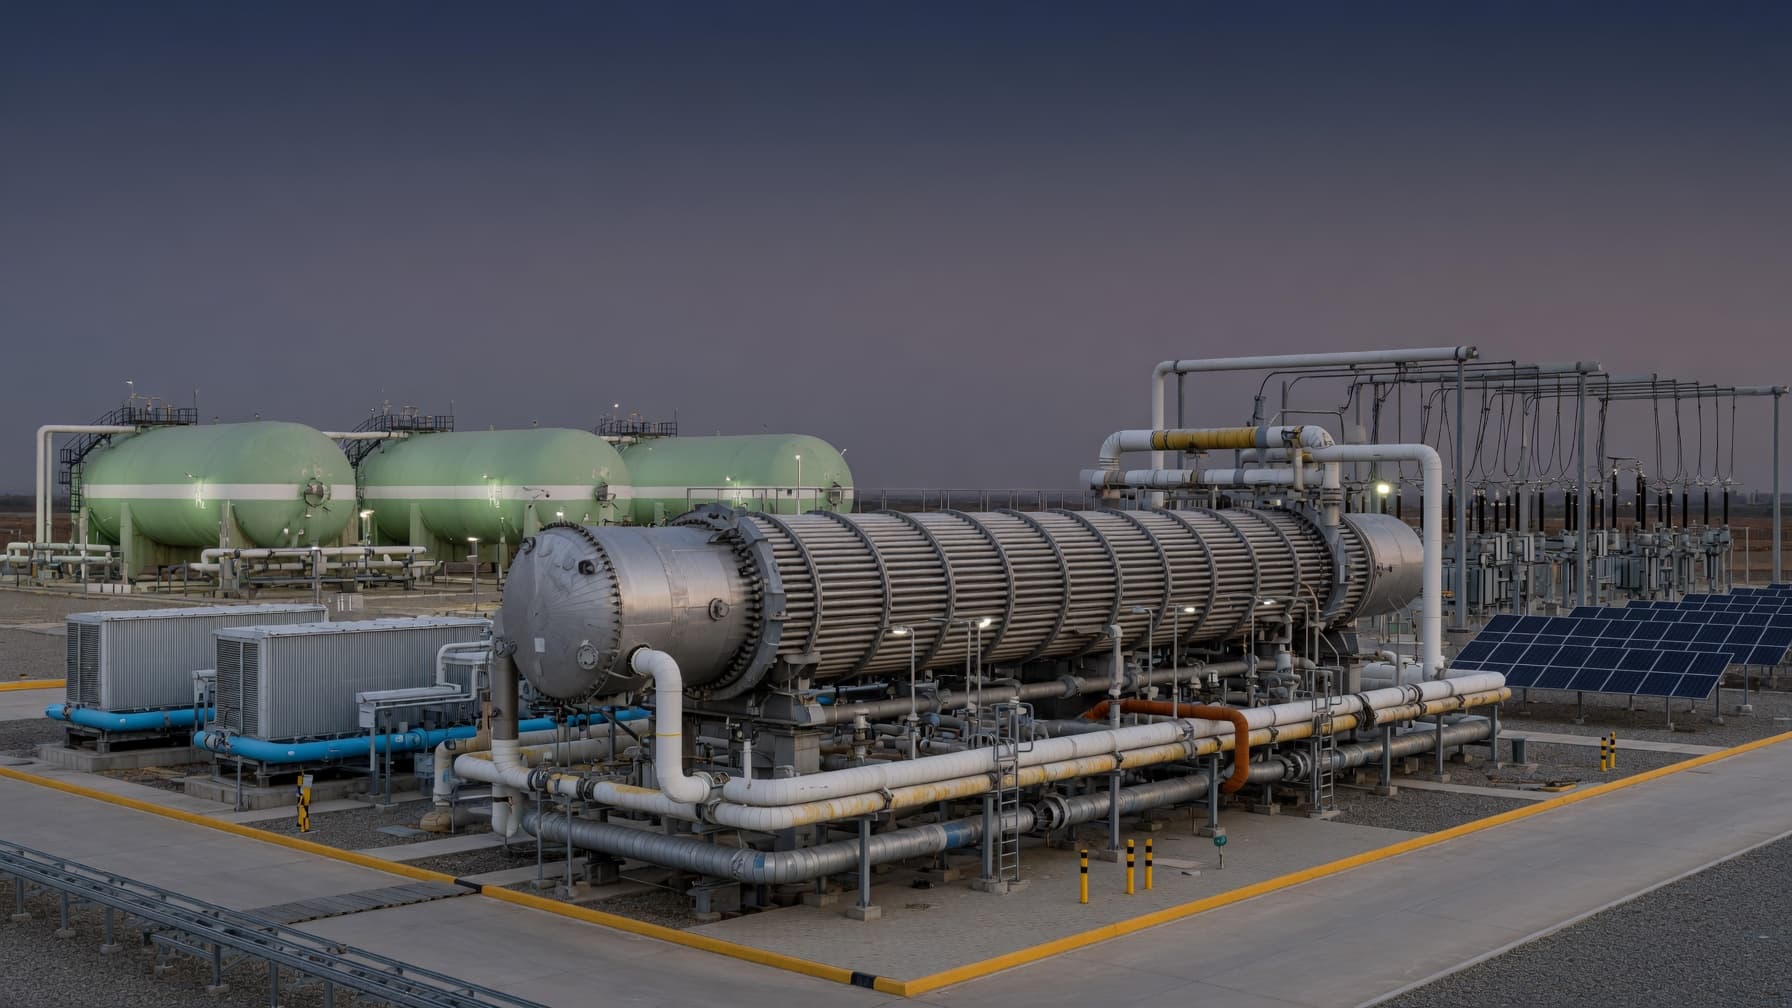
Carbon capture technologies address this challenge by separating carbon dioxide from industrial streams for storage or utilization.
At least 10 major chemical plant CCS projects are currently under development worldwide.
Applications include:
Ammonia production facilities.
Hydrogen generation units.
Integrated petrochemical complexes.
Renewable electricity procurement expanding rapidly
Renewable electricity procurement has evolved into a central pillar of chemical industry decarbonization.
Electricity demand is expected to increase as companies electrify processes and expand green hydrogen production capabilities.
Renewable power supports several applications:
Electrolysis systems used in green hydrogen generation.
Electrified process heating technologies.
Compression and utility operations across production sites.
Procurement strategies vary depending on regional market conditions.
Companies increasingly utilize:
Long-term power purchase agreements.
Direct investment in renewable assets.
Utility-based renewable sourcing programs.
These approaches help reduce Scope 2 emissions while supporting broader climate commitments.

Scope 3 engagement becoming a procurement priority
Scope 3 emissions present one of the most complex challenges for chemical companies.
These emissions originate throughout value chains and often exceed direct operational emissions.
As reporting expectations evolve, organizations increasingly require suppliers to provide transparent carbon data.
Key drivers include:
Compliance with carbon border adjustment mechanisms.
ESG disclosure obligations.
Customer expectations for product-level emissions transparency.
Procurement teams now evaluate suppliers using criteria beyond price and quality.
Important considerations include:
Availability of embedded carbon information.
Supplier decarbonization roadmaps.
Verification methodologies supporting reported emissions data.
This shift is transforming supplier relationships into collaborative partnerships focused on emissions reduction.
Building integrated decarbonization roadmaps
The future of chemical industry sustainability depends on integrated approaches rather than isolated initiatives.
Organizations achieving meaningful reductions typically combine multiple strategies tailored to operational realities.
Common elements include:
Immediate deployment of efficiency improvements.
Progressive adoption of renewable electricity.
Investment in lower-carbon feedstocks.
Strategic evaluation of carbon capture opportunities.
Enhanced engagement across supply chains.
No universal pathway exists.
Regional energy systems, regulatory frameworks and product portfolios all influence decarbonization priorities.

What procurement and sustainability teams should do now
Carbon reduction strategies are increasingly shaping competitiveness within the chemical industry.
Organizations that delay action may face growing regulatory exposure, supply chain disruptions and customer expectations that outpace existing capabilities.
Procurement and sustainability leaders should focus on:
Establishing reliable carbon accounting systems.
Engaging suppliers on emissions transparency initiatives.
Identifying opportunities for renewable energy integration.
Evaluating emerging technologies aligned with long-term business objectives.
The transition to lower-carbon chemical manufacturing will unfold over decades. However, many of the most impactful decisions will occur within the next few years.
Ready to source Methanol from verified global suppliers? Explore competitive offers on our platform today.
Methanol CAS: 67-56-1